
Is Toyota offering 0 financing deals for new vehicles? Yes, Toyota often provides special APR offers, but they change monthly. You need good credit to qualify for these low rates. Always check the official website for the latest promotions near you.
Key Takeaways
- Special APR Offers: Toyota frequently offers 0% or low APR financing on select new models.
- Credit Requirements: You usually need a high credit score to qualify for 0% financing deals.
- Model Specific: Not every car gets the deal; it depends on the specific trim and model.
- Loan Term Limits: 0% financing often comes with shorter loan terms like 36 or 48 months.
- Regional Differences: Offers vary by region and dealer, so check locally.
- Lease Alternatives: Sometimes low money factors on leases are better than 0% finance.
- Combine Offers: You often cannot combine 0% financing with other rebates simultaneously.
📑 Table of Contents
- Is Toyota Offering 0 Financing Deals Right Now?
- Understanding Toyota Special APR Offers
- Credit Score Requirements for 0% APR
- Which Toyota Models Qualify for Low Rates?
- 0% Financing Versus Cash Rebates
- Regional Differences and Dealer Variations
- Expert Insights on Toyota Financing
- Key Takeaways for Smart Buyers
Is Toyota Offering 0 Financing Deals Right Now?
Buying a new car is exciting. It is also a big financial decision. Many shoppers want to save money on interest. This leads to one common question. Is Toyota offering 0 financing options for new cars? The answer is not a simple yes or no. It depends on the time of year. It also depends on your credit score. Toyota Financial Services often runs promotions. These promotions can include very low APR rates. Sometimes they even offer 0% APR. But these deals are not permanent. They change every month. You need to know how to find them. You also need to know if you qualify.
This guide will help you understand these offers. We will look at how the deals work. We will discuss credit requirements. We will also compare financing to other options. By the end, you will know what to ask at the dealership. You can make a smart choice for your budget. Saving money on interest means more money for other things. Let us dive into the details of Toyota financing.
Understanding Toyota Special APR Offers
Toyota uses special financing to move inventory. They also want to reward loyal customers. These offers come from Toyota Financial Services. This is the lending arm of the company. They set the rates for the dealers. Sometimes a dealer can add their own incentives. But the base offer comes from the manufacturer. Is Toyota offering 0 financing on every model? No. Usually, the offer applies to specific vehicles. You might see it on a Toyota Camry. You might see it on a Toyota RAV4. It is less common on high-demand models.
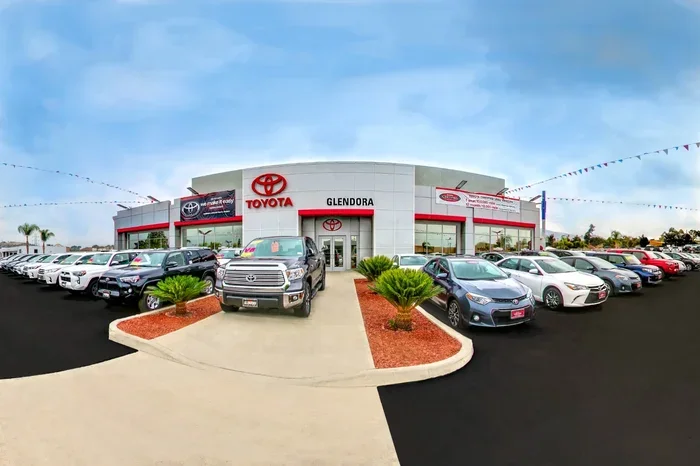
Visual guide about Toyota new car dealership
Image source: pictures.dealer.com
The APR rate is the cost of borrowing money. A lower rate means you pay less over time. A 0% rate means you pay no interest. This is a huge savings. On a thirty thousand dollar car, interest adds up fast. Over five years, even a small rate costs thousands. That is why people hunt for these deals. You should check the current offers online. The website lists national promotions. Your local dealer might have extra deals too.
How Monthly Promotions Work
Toyota changes offers every month. They might have a big push in June. Then they might change it in July. This is why timing matters. If you can wait, you might get a better rate. Sometimes end-of-month sales are better. Salespeople want to hit their targets. They might be more willing to work with you. You should also watch for holiday sales. Memorial Day or Labor Day often have specials. These events attract more buyers. Manufacturers respond with better financing.
You need to read the fine print. Some offers exclude certain trims. A base model might qualify. A luxury trim might not. Some offers exclude hybrid models. You need to ask specifically about your car. Do not assume the ad applies to everything. The advertisement says “select models.” This is a key phrase to watch.
Credit Score Requirements for 0% APR
Getting a low rate is not just about the car. It is about you too. Lenders look at your credit history. They want to know if you will pay them back. Is Toyota offering 0 financing to everyone? No. You usually need a high credit score. A score above 720 is ideal. Some offers require a score of 740 or higher. If your score is lower, you might get a higher rate. You might still get a good deal. But it will not be 0%.
Your debt-to-income ratio matters too. Lenders look at how much you owe. They compare it to how much you earn. If you have too much debt, you might not qualify. You should check your credit report before shopping. Fix any errors you find. Pay down small balances if you can. This can boost your score quickly. Even a small boost helps you qualify.
Steps to Improve Your Chances
You can take steps to prepare. First, check your credit score. Use a free service online. Second, gather your financial documents. You need proof of income. You need proof of residence. Having these ready speeds up the process. Third, get pre-approved elsewhere. This gives you a backup plan. If Toyota says no, you have another option. You can use that offer to negotiate.
Here are some quick tips for credit health:
- Pay bills on time every month.
- Keep credit card balances low.
- Do not open new credit cards before applying.
- Check for errors on your credit report.
- Keep old accounts open to show history.
Which Toyota Models Qualify for Low Rates?
Not all cars are the same. Some models sell faster than others. Manufacturers offer incentives on slower cars. They also offer incentives on new designs. Is Toyota offering 0 financing on the Toyota Camry? Often yes. The Camry is a popular sedan. It fits many budgets. The Toyota Corolla is another candidate. It is an affordable compact car. The Toyota RAV4 is a top SUV. It sometimes gets special rates too.
Trucks are different. The Toyota Tundra is a full-size truck. It holds value well. Sometimes the rates are higher on trucks. You might see low rates on the Toyota Tacoma instead. It depends on the current inventory. You should ask about the Toyota Highlander too. It is a family SUV. Families often look for low payments. The Toyota Sienna minivan might have offers. It is good to compare models.
Comparing Eligible Vehicles
You should compare the offers side by side. One model might have 0% financing. Another might have a cash rebate. You need to do the math. Sometimes a rebate is better. Sometimes 0% is better. It depends on the loan length. A shorter loan with 0% saves more interest. A longer loan with a rebate lowers the price. You need to choose what fits your budget.
Here is a comparison of common scenarios:
- 0% APR: Best for long-term savings on interest.
- Cash Rebate: Best for lowering the upfront price.
- Low APR: Good middle ground if 0% is unavailable.
- Lease Deal: Best for lower monthly payments short term.
0% Financing Versus Cash Rebates
This is a common dilemma. You see two different ads. One says 0% financing. The other says five thousand dollar rebate. Which one do you pick? You usually cannot have both. You must choose one option. Is Toyota offering 0 financing worth more than a rebate? It depends on the math. You need to calculate the total cost. A rebate lowers the principal amount. 0% lowers the interest cost.
If you plan to pay off the car fast, 0% is great. You avoid interest entirely. If you need a lower monthly payment, a rebate helps. It reduces the amount you borrow. This lowers the payment even with interest. You should use an online calculator. Plug in the numbers for both options. See which one costs less overall. Do not just look at the monthly payment. Look at the total price of the car.
When to Choose Each Option
Choose 0% financing if you have good credit. Choose it if you want a shorter loan term. Choose it if you plan to keep the car long. Choose a rebate if your credit is average. Choose it if you need a lower loan amount. Choose it if you plan to sell the car soon. Sometimes the rebate saves more money upfront. You can invest that savings elsewhere. The interest you save on 0% might be less than the rebate value.
Regional Differences and Dealer Variations
Offers are not the same everywhere. Toyota has regions in the United States. One state might have different deals. Another state might have different inventory. Is Toyota offering 0 financing in your city? You need to ask locally. A dealer in New York might have different offers. A dealer in California might have different offers. Supply and demand affect this. If a car is popular in your area, rates might be higher. If inventory is high, rates might be lower.
Dealers also have flexibility. They can sometimes adjust the rate. They want to make the sale. If you are a strong buyer, they might help. You should talk to the finance manager. Ask them about all available incentives. Ask if there are any regional specials. You might find something not listed online. Building a relationship helps too. Returning customers might get better treatment.
Questions to Ask Your Dealer
You should be prepared when you visit. Write down your questions beforehand. Do not rely on memory. Here are some good questions to ask:
- What is the current APR for this model?
- Are there any regional incentives available?
- Does this offer require a specific loan term?
- Can I combine this with loyalty rebates?
- What credit score is needed for the best rate?
Expert Insights on Toyota Financing
Experts suggest shopping around. Do not just take the first offer. Check with your local bank too. Sometimes your own bank has a good rate. You can compare that to Toyota Financial. Having multiple options gives you power. You can tell the dealer you have other offers. They might match or beat them. Is Toyota offering 0 financing better than a bank loan? Often yes, but not always. Banks might offer competitive rates for loyal customers.
Another tip is to focus on the out-the-door price. Financing is only part of the cost. The price of the car matters most. Negotiate the price first. Then talk about financing. If you mix the two, it gets confusing. Dealers might hide costs in the financing. Keep the negotiations separate. This ensures you get the best deal on both.
Common Mistakes to Avoid
Many buyers make mistakes during financing. They focus only on the monthly payment. This is a big error. A low payment might mean a long loan. A long loan means more interest. You might owe more than the car is worth. This is called being upside down. Avoid loans longer than sixty months. Try to keep it at forty-eight months or less. This saves money and builds equity faster.
Another mistake is skipping the fine print. Read every document before signing. Make sure the rate matches what you discussed. Check for added fees. Some dealers add unnecessary products. You do not have to buy them. Gap insurance is one example. It might be useful, but it costs extra. Decide if you really need it. Do not let them pressure you into add-ons.
Key Takeaways for Smart Buyers
To wrap up the main points, remember these things. Financing deals change often. You need good credit to get the best rates. Not every car qualifies for 0% APR. You must choose between rebates and low rates. Local dealers might have unique offers. Always read the contract carefully. Do not rush into a decision. Take your time to compare options.
Saving money on a car purchase takes effort. It pays off in the long run. You will have more money in your pocket. You will have less stress on your budget. Is Toyota offering 0 financing is a question with a changing answer. But now you know how to find it. You know what to look for. You know how to qualify. Go to the dealership with confidence. Ask the right questions. Drive home with a deal you love.
Frequently Asked Questions
How do I find current Toyota 0% financing offers?
You can check the official Toyota website for national offers. You should also call your local dealership for regional specials. Offers change monthly so verify the date.
What credit score is needed for Toyota 0% financing?
Typically you need a credit score of 720 or higher. Some promotions may require an even higher score. Check your credit report before applying.
Can I combine 0% financing with a cash rebate?
Usually you must choose one or the other. Manufacturers rarely allow both on the same vehicle. Calculate which option saves you more money.
Does 0% financing apply to all Toyota models?
No, it usually applies to select models and trims. Popular vehicles like the Camry or RAV4 often qualify. Exotic or high-demand trims might be excluded.
Is Toyota Financial Services the only lender for these deals?
Yes, these specific manufacturer offers usually require using Toyota Financial Services. You cannot use an outside bank for the 0% rate. You can use outside banks for standard rates.
Are there loan term restrictions for 0% APR?
Yes, 0% financing often comes with shorter terms. You might see 36 or 48 month limits. Longer terms usually have higher interest rates.