
Toyota often runs special financing events that include 0% APR offers. These deals change monthly and depend on your credit score, location, and the vehicle you choose. Not every buyer qualifies, so checking your credit and comparing rates matters. You can also combine low rates with incentives like cash rebates. Always read the fine print before signing any loan agreement.
Buying a new car should feel exciting, not confusing. One of the biggest questions buyers ask is does Toyota have 0 financing deals right now. The short answer is yes, Toyota sometimes offers 0% APR financing. But these offers are not available every day, and they are not for every buyer. Let us break down how these deals work, who qualifies, and how you can get the best rate possible.
Toyota Financial Services handles most dealer financing for Toyota vehicles. They run monthly incentive programs that can include low APR or zero percent interest. These promotions help move inventory and reward buyers with strong credit. If you time your purchase well, you might lock in a very low cost of borrowing. That can save you thousands over the life of the loan.
Before you head to the dealer, it helps to know what to expect. Financing offers change often, so a deal you saw last month may not exist today. Your credit, the model you want, and even your state can affect the offer. This guide will walk you through the details so you can shop with confidence.
Key Takeaways
- 0% APR offers exist: Toyota periodically releases 0% financing promotions for qualified buyers.
- Credit matters most: Lenders usually require excellent credit scores for zero percent deals.
- Promotions vary: Offers change by region, month, and model, so check local dealers.
- Rebates vs. low rates: You often must choose between 0% financing and cash rebates.
- Loan terms affect savings: Shorter terms with 0% APR maximize interest savings.
- Read the fine print: Some deals exclude certain models, trims, or regions.
- Shop around: Compare Toyota special financing with bank and credit union rates.
📑 Table of Contents
- What Does 0% Financing Mean for Toyota Buyers
- Does Toyota Have 0 Financing Right Now
- How Toyota Special Financing Deals Work
- Toyota 0% APR Eligibility and Credit Requirements
- Toyota Financing vs Bank and Credit Union Loans
- How to Get the Best Toyota Loan Deal
- Expert Insights on Toyota 0% Financing
- Key Takeaways
- Conclusion
What Does 0% Financing Mean for Toyota Buyers
Zero percent financing means you pay no interest on your auto loan. You borrow money and repay only the principal. That sounds simple, but the details matter. A 0% APR offer can make monthly payments smaller and reduce the total cost of the car. It is one of the best financing deals you can get, if you qualify.
Toyota uses these offers to promote certain models and trim levels. Not every vehicle qualifies. Sometimes the deal applies to specific SUVs, sedans, or trucks. Other times it covers the whole lineup for a limited time. You also usually need a strong credit score. Lenders want to reduce risk, so they reserve 0% APR for buyers with excellent credit histories.
It helps to understand the trade-offs. A 0% loan can save you a lot of money. But dealers may offer a cash rebate instead. You often cannot take both. If you choose 0% financing, you might give up a discount on the purchase price. That is why you should run the numbers before you decide.
How Zero Percent APR Works
When you accept 0% financing, the lender charges no interest. Your payment goes entirely toward reducing the loan balance. This is different from a low APR loan, where interest still adds to your cost. With 0% APR, the math stays simple. You pay the amount you borrowed, divided over the loan term.
Toyota Financial Services sets these promotions. They work with dealers to advertise special APR events. The offer appears in ads, emails, and on the Toyota website. You can also ask your local dealer about current deals. Always confirm the details in writing before you sign anything.
Who Usually Qualifies
Qualifying for 0% financing usually requires excellent credit. Lenders look at your credit score, payment history, and debt load. They also check your income and employment. If you have late payments, high balances, or recent credit issues, you may not qualify. That does not mean you cannot get a good rate. It just means 0% may not be available to you.
Other factors matter too. Some offers require a minimum loan amount. Others exclude certain models or options. A few promotions apply only to well-qualified buyers. That phrase sounds vague, but it usually means top-tier credit and a stable financial profile. If you are unsure, ask the dealer what standards they use.
Does Toyota Have 0 Financing Right Now
The answer changes often, but does Toyota have 0 financing promotions? Yes, Toyota runs 0% APR events from time to time. These offers appear during special financing events and model year transitions. They can also show up when inventory needs to move. Since offers shift monthly, you should verify what is active today.

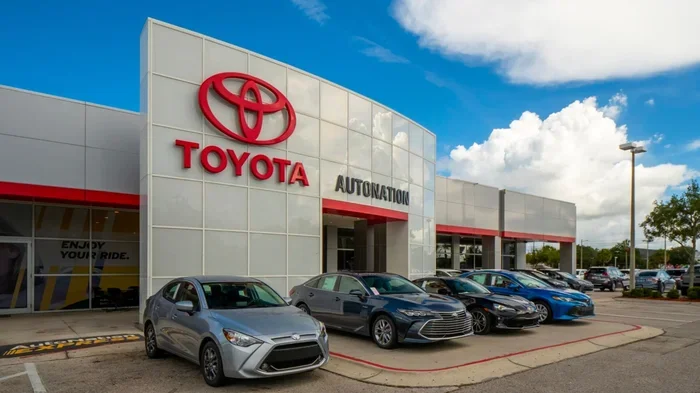
Visual guide about Toyota dealership new car financing
Image source: moneyhub.co.nz
Toyota Financial Services publishes incentive programs for different regions. Some areas get better deals than others. Certain models may have longer promotional windows. For example, popular sedans and compact SUVs sometimes get special APR offers. Trucks and larger SUVs may have different terms. The best move is to check current incentives before you shop.
You can also look at seasonal timing. End-of-month, end-of-quarter, and holiday sales events often bring stronger financing deals. Dealers may stack incentives to close more sales. If you are flexible on timing, you can wait for a better window. If you need a car now, compare the current offer with other financing options.
Checking Current Toyota Incentives
Start with the official Toyota incentives page for your region. Look for special APR offers and note the eligible models. Then call a few dealers and ask the same question. Dealers sometimes know about local promotions that are not easy to find online. Ask them to spell out the exact terms, including the APR, loan length, and any restrictions.
Keep a simple list as you compare offers. Write down the model, trim, APR, loan term, and any down payment requirements. This makes it easier to spot the best deal. It also helps you avoid confusion when multiple dealers give you different numbers. Clear notes keep the process smooth.
When Toyota Runs Special Financing Events
Toyota often times promotions around key sales periods. These can include holiday weekends, model year changeovers, and regional events. During these windows, 0% APR offers may appear more often. Inventory levels also matter. When a dealer has too many of one model, they may push financing incentives to attract buyers.
If you can wait, monitor these cycles. If you cannot wait, do not assume you missed everything. Even if 0% is not available, low APR offers may still exist. A low rate combined with a rebate can be a strong deal. The goal is to reduce your total cost, not just chase a headline.
How Toyota Special Financing Deals Work
Toyota special financing deals are structured to reward qualified buyers. The dealer and Toyota Financial Services agree on the promotion. Then the dealer applies it to eligible vehicles and buyers. The process looks simple, but several pieces fit together. You need to understand the APR, the term, and any limits on the offer.
A typical offer might say 0% APR for 36 months. That means you pay no interest for three years. Shorter terms usually come with 0% financing because the lender takes less risk. Longer terms may have higher rates. If you want a longer loan, you may need to accept some interest. That is why term length matters a lot.
Another common structure is a choice between 0% financing and a cash rebate. This is important. If you take the rebate, you may pay interest on the remaining loan. If you take 0%, you skip the rebate. You should compare both paths. Sometimes the rebate wins, especially if you plan to pay the loan off quickly.
Common Offer Structures
Here are the most common Toyota financing structures you may see:
- 0% APR for a short term: Usually 24 to 36 months for well-qualified buyers.
- Low APR for a longer term: A small interest rate over 48 to 72 months.
- Cash rebate instead of 0%: A purchase discount that may pair with a standard rate.
- Regional or model-specific offers: Deals that apply to certain vehicles or areas.
Rebates Versus Low APR
This choice comes up a lot. A rebate lowers your price today. 0% financing lowers your interest cost over time. If you keep the loan for the full term, 0% can be very valuable. If you pay off the loan early, the rebate may matter more. The best choice depends on your budget and your plans.
Run a quick comparison. Calculate the total cost with 0% financing. Then calculate the total cost with a rebate and a standard APR. Include taxes, fees, and any down payment. The numbers will show you which option saves more. Do not guess. Use a simple calculator and keep the math clear.
Toyota 0% APR Eligibility and Credit Requirements
Credit requirements are the biggest hurdle for 0% financing. Lenders want to minimize risk, so they reserve the best rates for the strongest applicants. That usually means excellent credit, stable income, and a clean payment history. If your credit is good but not excellent, you may still get a low rate, just not 0%.
Your debt-to-income ratio also matters. Lenders look at how much you owe compared with your income. If your monthly obligations are high, they may decline the best offer. A larger down payment can help in some cases. It lowers the loan amount and shows commitment. Still, credit score remains the main factor.
If you are not sure where you stand, check your credit before you shop. Review your report for errors. Pay down balances if you can. Avoid opening new credit lines right before the purchase. These steps can improve your chances of qualifying for the best offer.
Credit Score and Approval
There is no single cutoff that applies everywhere. Different lenders and dealers may use different standards. In general, top-tier credit gives you the best shot at 0% APR. If your score is lower, ask about other financing options. A low APR from a bank or credit union may still be a strong deal.
Approval also depends on the full application. Income, employment, and recent credit activity all play a role. A clean, stable profile works in your favor. If you have had recent issues, be ready to explain them. Transparency helps the lender understand your situation.
Ways to Improve Your Chances
You can take a few practical steps before applying:
- Check your credit report: Fix errors and note any negative items.
- Lower card balances: Reducing utilization can help your score.
- Save for a down payment: A larger down payment can strengthen the deal.
- Keep paperwork ready: Pay stubs, ID, and proof of insurance help the process.
- Avoid new debt: Do not open new accounts right before the loan.
Toyota Financing vs Bank and Credit Union Loans
Dealer financing is convenient, but it is not the only option. Banks and credit unions also offer auto loans. Sometimes they beat dealer rates, especially if you have a strong relationship with them. Other times Toyota special financing wins because of the 0% APR or a rebate. You should compare all three before you decide.
Dealer financing has clear advantages. It keeps everything in one place. You can often apply quickly and get a decision fast. Toyota Financial Services also knows the vehicle and the incentives well. That can make the process smoother. But convenience does not always mean the lowest cost.
Banks and credit unions may offer more transparency. You can get pre-approved before you visit the dealer. That gives you a baseline to compare against. If the dealer beats your pre-approved rate, great. If not, you still have a solid backup. This approach puts you in control.
Comparing Dealer Offers
When you compare offers, look at the total cost, not just the monthly payment. A low payment can hide a longer term or extra fees. Ask for the APR, the loan length, the total interest, and the payoff amount. Then compare those numbers side by side. The clearest picture comes from total cost.
You should also ask about prepayment rules. Some loans let you pay early without penalties. Others may have restrictions. If you plan to pay off the car early, this matters. A 0% loan that allows early payoff can be especially useful. You get the interest savings and the flexibility.
When Outside Financing Wins
Outside financing can win in a few situations. If your credit qualifies you for a very low bank rate, that may beat a dealer offer with fees. If you want a longer term, a credit union may give you a better rate than the dealer. If the dealer cannot match your pre-approval, use it as leverage. Sometimes the dealer will improve the offer to keep your business.
Do not forget to factor in incentives. A dealer may offer 0% APR or a rebate that a bank cannot match. In that case, dealer financing may be the better path. The best choice depends on the numbers, not the source. Compare the full package and choose what saves you the most.
How to Get the Best Toyota Loan Deal
Getting the best deal takes a little preparation. Start by deciding what you can afford. Look at the total budget, not just the monthly payment. Include insurance, fuel, maintenance, and taxes. A car that fits your payment but stretches your budget can create stress later. A realistic budget keeps the purchase comfortable.
Next, gather your financing options. Check Toyota incentives, then get pre-approved by a bank or credit union. Now you have a baseline. Visit the dealer and ask about current 0% or low APR offers. Compare the numbers calmly. If one option is better, take it. If not, negotiate with the information you have.
Negotiation matters. You can discuss the vehicle price, the down payment, and the financing terms. A lower price can make any loan cheaper. A smaller loan amount can also improve your approval odds. Keep the conversation focused on the total cost. That is the number that affects your wallet most.
Negotiating the Best Terms
Use these tips when you negotiate:
- Focus on the out-the-door price: This includes fees, taxes, and any add-ons.
- Ask for the APR in writing: Confirm the rate before you sign.
- Compare term lengths: Shorter terms usually cost less overall.
- Check for add-ons: Decline extras you do not need.
- Keep emotions in check: Stay calm and ready to walk away if needed.
Common Mistakes to Avoid
A few mistakes can cost you money. Do not focus only on the monthly payment. Do not skip the credit check before shopping. Do not assume 0% is available without verifying it. Do not rush into add-ons you do not need. And do not forget to read the contract carefully. Small details can change the deal significantly.
Another common mistake is mixing up incentives. Some buyers think they can take both 0% financing and a cash rebate. Often that is not allowed. Ask clearly which incentives apply together. Then choose the option that gives you the best overall value. Clear questions prevent surprises at signing.
Expert Insights on Toyota 0% Financing
Experts usually say the same thing: read the offer carefully and compare the total cost. 0% financing can be a great deal, but only if it fits your situation. If you can pay off a short-term loan quickly, the savings can be substantial. If you need a longer term, a low APR with a rebate may make more sense. There is no one-size-fits-all answer.
Another expert tip is to keep your options open. Do not fall in love with one financing offer before you compare others. Dealer incentives change, and your credit profile may improve with a little time. If you can wait for a better promotion, you might save more. If you cannot wait, compare the current offer with outside financing and choose the best value.
Finally, keep the process simple. Ask direct questions. Get the numbers in writing. Compare total costs. Make the choice that fits your budget and your goals. That approach works far better than chasing a catchy headline.
Key Takeaways
Here is a quick recap to keep in mind:
- 0% financing exists sometimes: Toyota runs special APR events for qualified buyers.
- Credit is crucial: Excellent credit gives you the best chance at 0% APR.
- Compare rebate vs. rate: You may need to choose between 0% financing and a cash discount.
- Check current offers: Promotions change by month, region, and model.
- Compare total cost: Look at APR, term, fees, and payoff amount together.
- Get pre-approved: Outside financing gives you leverage and a backup plan.
- Read the contract: Confirm the rate, term, and any restrictions before signing.
Conclusion
So, does Toyota have 0 financing options? Yes, Toyota offers 0% APR promotions at times, but these deals are limited and depend on your credit, the model, and the current incentive program. That means you need to check active offers, compare them with other financing, and choose the option that saves you the most money overall.
The best approach is simple. Know your budget, check your credit, and compare dealer offers with bank or credit union loans. Look at the total cost, not just the monthly payment. If 0% financing fits your situation, it can be a powerful way to reduce interest costs. If not, a low APR or a rebate may still give you a great deal.
Take your time, ask clear questions, and keep the numbers in writing. With a little preparation, you can find a Toyota loan that matches your goals and your budget. That is the smartest way to buy with confidence.
Frequently Asked Questions
Does Toyota offer 0% financing on all models?
No, Toyota does not offer 0% financing on every model. These promotions usually apply to selected vehicles, trims, or regions for a limited time. Always check the current incentive list before you shop.
What credit score do I need for Toyota 0% financing?
You generally need excellent credit to qualify for 0% APR. Lenders also review your income, debt, and payment history. If your credit is strong, you have a better chance of approval.
Can I combine 0% financing with a Toyota cash rebate?
Often you must choose one or the other. Many promotions let you take 0% APR or a cash rebate, but not both. Compare the total cost of each option before you decide.
How long do Toyota 0% APR offers last?
These offers usually run for a limited promotional period. They can change monthly, and some deals have short loan terms. Verify the current offer details with the dealer or Toyota Financial Services.
Is dealer financing better than a bank loan for a Toyota?
It depends on the numbers. Dealer financing may include 0% APR or rebates that banks cannot match. A bank or credit union may offer a better rate in other cases. Compare the total cost of both options.
What should I ask before signing a Toyota financing contract?
Ask for the APR, loan term, total interest, fees, and any restrictions on the offer. Confirm whether the rate is fixed and whether early payoff is allowed. Get every detail in writing before you sign.