Leasing a Toyota Corolla usually costs between $250 and $400 per month, depending on your credit score, down payment, and chosen trim. The exact price changes with current money factors, residual values, and local taxes, so shopping around matters. This guide explains how much to lease a Toyota Corolla, what drives the monthly payment, and how to negotiate better terms. You will also learn about mileage caps, wear-and-tear rules, and end-of-lease options. Read on to make a confident, budget-friendly decision.
If you want a reliable sedan without a huge monthly payment, leasing can be a smart move. The Toyota Corolla remains one of the most popular compact cars in the country. It is affordable, efficient, and easy to live with every day. That combination makes it a top choice for car leasing too. Many buyers ask the same question: how much to lease a Toyota Corolla? The short answer depends on several moving parts, including trim level, credit profile, down payment, and current market rates.
This guide walks you through the real costs, the hidden details, and the best ways to lower your payment. We will keep things simple and practical. You will learn what dealers include in the monthly number, how mileage affects the price, and what to watch for before you sign. By the end, you will know exactly what to expect and how to get a fair deal.
Key Takeaways
- Monthly payments typically range from $250 to $400 for a Toyota Corolla lease, depending on trim, credit, and location.
- A larger down payment lowers your monthly cost but increases your upfront risk if the car is totaled or stolen.
- Mileage limits usually sit at 10,000, 12,000, or 15,000 miles per year, and extra miles cost more at the end.
- Your credit score heavily impacts the money factor, which is the lease equivalent of an interest rate.
- Gap insurance is often included in Toyota leases, protecting you if the car is totaled before the lease ends.
- End-of-lease options include returning the car, buying it, or leasing another vehicle, so plan ahead.
- Shopping multiple dealers and comparing lease deals is the fastest way to find the best price.
📑 Table of Contents
- How Much to Lease a Toyota Corolla: The Real Monthly Cost
- Understanding Lease Terms Before You Sign
- How Down Payments and Fees Change the Price
- Toyota Corolla Lease Deals and Incentives
- End-of-Lease Options and Hidden Considerations
- Smart Tips to Lower Your Toyota Corolla Lease Payment
- Common Mistakes to Avoid
- Key Takeaways
How Much to Lease a Toyota Corolla: The Real Monthly Cost
Most shoppers start with one number in mind: the monthly payment. For a Toyota Corolla lease, that number usually lands between $250 and $400 per month for a standard trim with a typical down payment. The exact figure changes based on the model year, the dealer region, and the current lease incentives. A base LE trim often costs less than a sportier SE or a premium XSE trim. That difference shows up in the monthly payment because the vehicle price and residual value change.
It helps to think of a lease as paying for the car’s depreciation during the time you use it. You are not buying the whole vehicle. You are paying for the value it loses, plus finance charges and taxes. That is why the monthly lease payment can feel lower than a loan payment for the same car. You also return the car at the end, which removes resale worries. If you want to compare options, you can review how much is it to lease a Toyota Corolla for a closer look at current pricing patterns.
What Drives the Monthly Payment
Several factors work together to shape your final number. The most important ones include:
- Capitalized cost: This is the negotiated price of the car before lease math starts.
- Residual value: This is the estimated value of the car at the end of the lease.
- Money factor: This is the lease version of an interest rate. A lower number means a cheaper lease.
- Down payment or cap cost reduction: This lowers the amount you finance each month.
- Sales tax and fees: These vary by state and can raise the payment more than expected.
If you want a deeper understanding of how the vehicle’s specs affect value, you can also read how much horsepower does a Toyota Corolla have. Knowing the trim differences can help you choose between a lower payment and a more equipped car.
Quick Example Lease Math
Here is a simple example to show how the numbers can look. Imagine a Corolla with a capitalized cost of $24,000 and a residual value of $15,000 after three years. That means the depreciation portion is $9,000 over the lease term. Divide that by 36 months, and you get $250 for depreciation alone. Add the finance charge and taxes, and the payment rises. A down payment can reduce the monthly amount, but it also changes your total cash outlay.
This is why two people can lease the same car and see different payments. One buyer may put more money down. Another may have a stronger credit profile and qualify for a better money factor. A third may live in a state with higher taxes. Small differences add up quickly.
Understanding Lease Terms Before You Sign
Lease paperwork can feel confusing at first. The good news is that the core terms are simple once you know what they mean. When you understand the language, you can compare offers with confidence. You will also spot unnecessary add-ons that inflate the price.
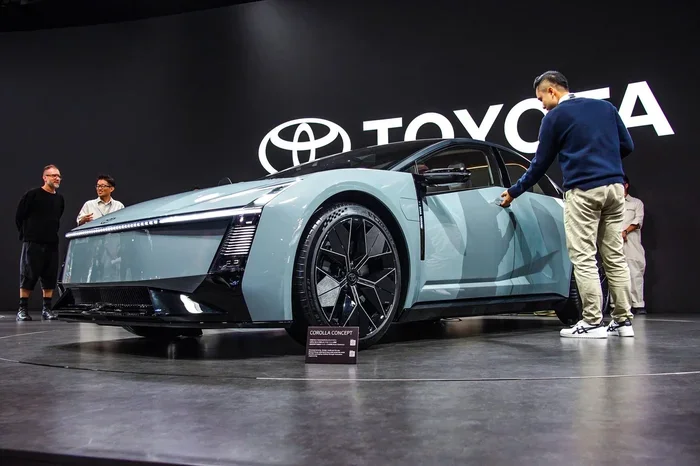
Visual guide about Toyota Corolla lease concept
Image source: images.carexpert.com.au
Money Factor and APR
The money factor is one of the most important lease numbers. It looks small, like 0.00125, so it can seem harmless. In reality, it controls the finance charge on the lease. To compare it with a loan, you can multiply the money factor by 2,400 to get an approximate APR. A lower money factor is better. Your credit score plays a big role here, along with current manufacturer lease programs.
Residual Value Matters More Than You Think
The residual value is the predicted worth of the car at lease end. A higher residual value usually helps the lessee because you pay for less depreciation. That is one reason compact cars like the Corolla can be attractive lease choices. They tend to hold value well. If you are comparing different Toyota models, you may also want to look at how much is a Toyota Corolla Cross to see how crossover pricing differs from the sedan.
Mileage Limits and Excess Mileage Charges
Most leases come with a yearly mileage cap. Common options are 10,000, 12,000, and 15,000 miles. If you drive more than the limit, you pay an excess mileage fee at the end. That fee is often charged per mile over the allowance. It can become expensive fast if you underestimate your driving habits.
Before you choose a mileage plan, think about your real routine. Commuting, school runs, road trips, and weekend errands all count. If you are unsure, it is usually safer to pick a higher mileage limit upfront than to pay penalties later. You can also check related ownership details like how many miles per gallon Toyota Corolla gets, since fuel economy affects your total cost of use.
How Down Payments and Fees Change the Price
A down payment on a lease is often called a cap cost reduction. It lowers the amount you finance, which reduces the monthly payment. That sounds great, but it is not always the best move. If the car is stolen or totaled early in the lease, that upfront money may not come back to you in the same way a loan down payment might. Gap coverage can help, but you still lose the cash you handed over.
Because of that risk, many lease experts suggest keeping the down payment low. Instead, they recommend focusing on a strong negotiated price and a healthy trade-in if you have one. You can also use a due-at-signing figure that includes first month’s payment, registration, and small fees without stacking extra cash into the lease.
Common Fees to Expect
When you review a lease quote, look for these typical costs:
- Acquisition fee: A charge from the leasing company to set up the lease.
- Disposition fee: A fee that may apply at lease return if you do not buy the car.
- Registration and title fees: Local costs that vary by state.
- Documentation fee: A dealer charge for processing paperwork.
- Sales tax: Often applied differently depending on your state’s lease tax rules.
Some fees are fixed. Others can be negotiated or reduced. A dealer may be willing to adjust the vehicle price or remove certain add-ons. It helps to ask for a line-item breakdown instead of just a monthly payment number.
Toyota Corolla Lease Deals and Incentives
Lease offers change often, and the best deal depends on the model year and region. Manufacturers sometimes provide special lease programs with lower money factors or stronger residuals. Dealers may also run limited-time promotions. If you are shopping for a newer model, it can be useful to compare the Corolla with other popular Toyota choices, such as how much is a brand new Toyota Prius, especially if fuel efficiency matters to you.
How to Spot a Good Deal
A strong lease deal is not only about a low monthly payment. It is about the full package. Look for these signs:
- A fair negotiated price on the car
- A money factor that matches or beats current market offers
- Reasonable mileage allowance for your driving habits
- Minimal unnecessary add-ons
- Clear disclosure of all fees and taxes
If you want to compare sedan options more broadly, you can also review how much does a new Toyota Camry cost. A Camry lease may make sense if you need more rear-seat room or a larger feel, though the Corolla usually stays cheaper.
Timing Your Lease
Lease pricing can shift with model-year changes, inventory levels, and seasonal promotions. End-of-month and end-of-quarter periods sometimes bring more active dealer incentives. New model arrivals can also affect how dealers price remaining stock. If you are flexible, it pays to watch several dealers and compare offers over time.
End-of-Lease Options and Hidden Considerations
At the end of the lease, you usually have a few choices. You can return the car, purchase it for the agreed residual value, or lease another vehicle. Each option has pros and cons. Returning the car is simple, but you need to stay within the wear-and-tear guidelines. Buying it can make sense if the car is in great shape and the market value is higher than the purchase price. Leasing another vehicle can be convenient if you enjoy driving a new car every few years.
Wear-and-Tear Rules
Lease returns are not judged only on mileage. They are also checked for damage beyond normal use. Small scratches, dents, worn tires, and interior damage can lead to extra charges. To avoid surprises, keep up with basic care and fix minor issues before the return inspection if the cost is lower than the potential penalty.
Gap Coverage and Insurance
Many Toyota leases include gap coverage, which helps cover the difference between what the car is worth and what you still owe if it is totaled. That protection is valuable because lease balances can sometimes be higher than the car’s actual cash value early in the term. Still, you should confirm the coverage details before signing. Insurance requirements can also be stricter on leases than on loans, so check your policy limits.
If you want to compare ownership costs across different Toyota vehicles, you may find it helpful to read how much does a Toyota 4Runner cost. SUVs often have different lease structures and insurance considerations than compact sedans.
Smart Tips to Lower Your Toyota Corolla Lease Payment
If you want the best possible deal, a little strategy goes a long way. The goal is to reduce the capitalized cost, secure a favorable money factor, and avoid paying for things you do not need. Here are practical steps that can help.
Negotiate the Price First
Always negotiate the vehicle price before talking about the monthly payment. Dealers can adjust terms to make a payment look attractive while hiding a higher price. Start with the out-the-door cost of the car, then move to lease specifics. This keeps the discussion transparent.
Keep the Down Payment Modest
A smaller down payment can reduce your risk while still giving you a workable monthly number. If you have a trade-in, that can serve as part of the deal instead of large cash upfront. The key is to preserve flexibility and avoid overcommitting cash at signing.
Choose the Right Mileage Plan
Pick the mileage limit that matches your actual driving. If you usually drive about 12,000 miles a year, do not automatically choose 10,000 miles to save a little now. The excess mileage charges later may cost far more. It is easier to plan ahead than to pay penalties at the end.
Watch the Add-Ons
Dealers may offer extras such as paint protection, fabric guard, wheel locks, or extended service plans. Some of these may be useful, but many are not necessary on a short-term lease. Ask yourself whether the add-on will still benefit you when the lease ends. If not, it may be better to skip it.
Compare Multiple Quotes
Do not stop at the first offer. Get lease quotes from several dealers if you can. Compare the vehicle price, money factor, fees, and total due at signing. A little shopping can reveal a much better deal. If you are also considering other Toyota models, you might glance at how much is a used Toyota Camry to understand how used pricing differs from a new lease.
Expert Insight
The best lease customers usually ask clear questions and compare numbers carefully. They do not focus only on the monthly payment. They look at the whole deal and choose the option that fits their budget and driving habits. That approach usually leads to a better outcome.
Common Mistakes to Avoid
Leasing is straightforward when you know the traps. Here are the most common mistakes shoppers make:
- Focusing only on the monthly payment: This can hide a poor vehicle price or high fees.
- Putting too much cash down: This increases risk if the car is damaged early.
- Underestimating mileage: This leads to surprise charges at lease end.
- Skipping the fine print: Fees, taxes, and wear-and-tear rules matter.
- Ignoring credit preparation: A better credit profile can improve lease terms.
- Assuming every dealer offers the same deal: Pricing and incentives can vary widely.
Key Takeaways
Leasing a Toyota Corolla can be a practical way to drive a dependable car with a manageable payment. The best results come from understanding the lease math, comparing offers, and choosing terms that match your life. Keep an eye on the capitalized cost, money factor, mileage allowance, and total cash due at signing. When you shop carefully, you can find a lease that feels comfortable and predictable.
If you are still deciding between leasing and buying, think about how long you want to keep the car and how much you drive. A lease works well for drivers who like a new vehicle every few years and want lower monthly payments. A purchase may be better if you plan to keep the car for a long time. Either way, knowing how much to lease a Toyota Corolla gives you a stronger starting point for your decision.
Frequently Asked Questions
How much does it usually cost to lease a Toyota Corolla each month?
A Toyota Corolla lease often falls between $250 and $400 per month, depending on trim, credit, down payment, and local taxes. The final amount changes with current incentives and the negotiated vehicle price. Comparing several offers is the best way to find your true cost.
What credit score do I need to lease a Toyota Corolla?
Most lenders prefer good to excellent credit for the best lease terms. A stronger credit profile usually helps you qualify for a lower money factor, which reduces the finance charge. If your score is lower, you may still get approved, but the payment could be higher.
Is it better to put money down on a car lease?
A down payment can lower the monthly payment, but it also increases your risk if the car is totaled or stolen early in the lease. Many shoppers prefer a smaller due-at-signing amount and focus on negotiating a better vehicle price instead. Always weigh the monthly savings against the upfront cash at risk.
What happens if I drive more miles than my lease allows?
If you exceed the mileage limit, you usually pay an excess mileage charge per mile at the end of the lease. That cost can add up quickly, so it is smart to choose a mileage plan that matches your real driving habits. If you expect higher mileage, selecting a larger allowance upfront is often cheaper.
Can I buy the Toyota Corolla at the end of the lease?
Yes, most leases include a purchase option at the agreed residual value. This can make sense if the car is in good condition and the market value is higher than the buyout price. Before deciding, compare the purchase price with the cost of leasing or buying another vehicle.
What should I look for when comparing Toyota Corolla lease offers?
Look at the vehicle price, money factor, mileage allowance, fees, taxes, and total amount due at signing. A low monthly payment is not enough if the car price or fees are too high. The best offer is the one that gives you the strongest overall value for your budget and driving needs.